
Apple Appoints Salman Dar to Lead Pakistan Affairs
September 15, 2026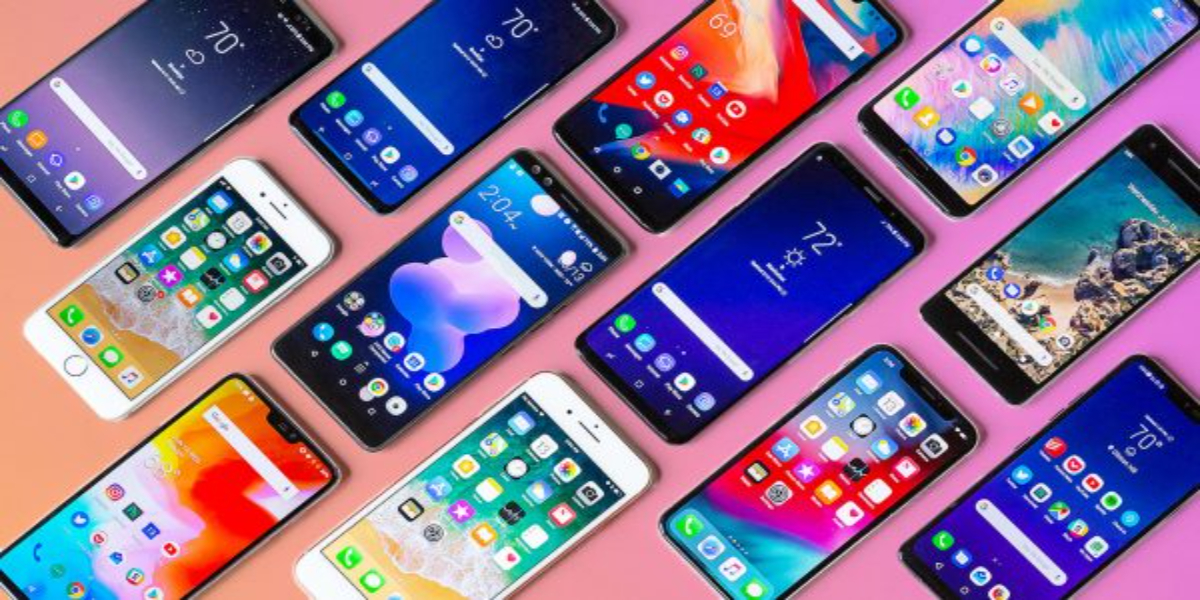
The Federal Board of Revenue has introduced an instalment facility for sales tax on imported mobile phones under the revised Ninth Schedule of the Sales Tax Act, allowing eligible individuals to spread their tax payments while requiring the full amount to be cleared within the same financial year.
The Federal Board of Revenue (FBR) has introduced a new facility allowing individuals to pay sales tax on imported mobile phones in instalments, providing greater flexibility for consumers registering devices through the Pakistan Telecommunication Authority’s (PTA) Device Identification, Registration and Blocking System (DIRBS).
The measure was introduced through amendments to the Ninth Schedule of the Sales Tax Act, 1990 under the Finance Act 2026. The FBR subsequently clarified the provision through Sales Tax Circular No. 1 of 2026.
According to the FBR, the revised provision allows an individual liable to pay tax on an imported mobile phone through the PTA’s DIRBS system to settle the tax through instalments under the prescribed mechanism. However, the facility comes with an important condition: all instalments must be paid before the end of the financial year in which the phone is imported.
The amendment does not reduce the applicable tax on imported mobile phones. Instead, it changes the payment mechanism by allowing eligible individuals to divide their tax liability into multiple payments rather than paying the entire amount upfront.
As Business Recorder reported, the Finance Act 2026 allows Pakistani citizens to pay the tax in instalments on imported mobile phones from July 1, 2026. The report noted that the Ninth Schedule of the Sales Tax Act was amended to introduce the facility.
The FBR’s clarification further explains that the provision forms part of the broader changes introduced through the Finance Act 2026 and is intended to facilitate taxpayers while retaining the existing tax recovery framework.
The amendment states that an individual may be allowed to pay the tax in instalments, subject to the condition that “all the instalments shall be paid before the end of the financial year”.
The development could ease the immediate financial burden for people importing smartphones, particularly where the applicable tax represents a significant portion of the device’s overall cost. At the same time, the government retains a firm deadline for complete payment, ensuring that the tax liability does not remain outstanding beyond the relevant financial year.
The change also clarifies that PTA’s role remains linked to the DIRBS registration and blocking system, while the taxation framework falls under the FBR. Recent parliamentary discussions have also highlighted the need for a more flexible mechanism for imported-phone taxes.
Overall, the new arrangement gives eligible mobile-phone importers more flexibility in managing their tax payments without changing the underlying tax liability or the requirement to clear the full amount within the prescribed financial year.